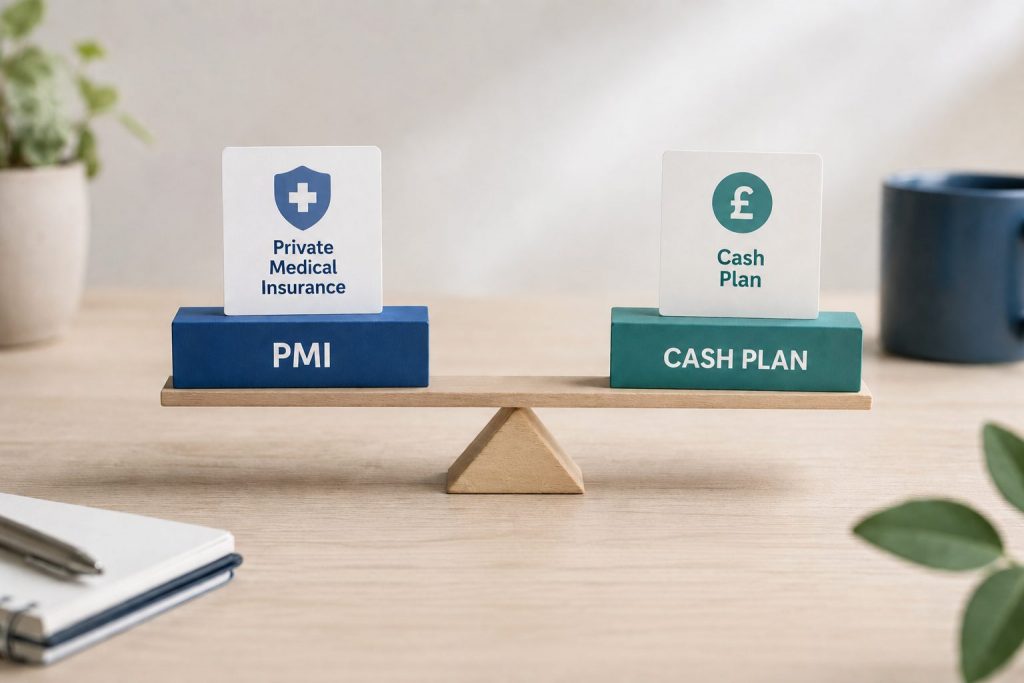
When people start looking into health cover, two options come up repeatedly: Private Medical Insurance (PMI) and Health Cash Plans. They sound similar, but they work in fundamentally different ways.
What Is Private Medical Insurance?
PMI is comprehensive health cover designed to pay for private medical treatment directly. When you need care, your insurer typically settles the bill with the hospital or clinic on your behalf.
What PMI usually covers:
- Consultations with specialists
- Diagnostic tests (MRI, CT scans, blood work)
- Inpatient and day-patient surgery
- Cancer treatment
- Physiotherapy and rehabilitation
- Mental health support (on many policies)
The key advantage is speed and choice. You skip NHS waiting lists, select your consultant, and often receive treatment within days rather than weeks or months.
PMI is underwritten, meaning your premium reflects factors like age, medical history, and the level of cover you choose. Policies range from basic plans covering core treatments to comprehensive options including outpatient care, therapies, and even dental or optical add-ons.
What Is a Health Cash Plan?
A cash plan works differently. Rather than paying providers directly, it reimburses you a fixed amount toward everyday health costs after you’ve paid upfront.
Common cash plan benefits:
- Optical (eye tests, glasses, contact lenses)
- Dental check-ups and treatment
- Physiotherapy and chiropractic sessions
- Health screenings
- Prescriptions
Cash plans have fixed payout limits – for example, up to £100 per year toward dental or £150 toward optical. They’re not designed to cover major medical treatment; they’re budgeting tools that help spread the cost of routine care.
Because there’s typically no medical underwriting, cash plans are easy to set up and premiums are low – often under £15 per month for individuals.
Key Differences at a Glance
| Feature | Private Medical Insurance | Health Cash Plan |
|---|---|---|
| Purpose | Comprehensive private treatment | Cashback on routine costs |
| Payment model | Insurer pays provider directly | You pay, then claim set amount reimbursement |
| Typical cover | Surgery, diagnostics, cancer, specialists | Dental, optical, therapies |
| Waiting lists | Bypasses NHS queues | Doesn’t affect NHS access |
| Underwriting | Yes – medical and lifestyle questions | Usually none |
| Cost | Higher (scales with cover and risk) | Lower (fixed, predictable) |
Ready to find the right cover?
Can You Have Both?
Absolutely – and many people do. A cash plan tops up the areas PMI often excludes (routine dental, glasses, chiropractor visits), while PMI handles the bigger, more expensive treatments you couldn’t easily fund yourself.
Think of it this way:
- PMI protects you from significant, unexpected health costs.
- A cash plan helps you manage predictable, ongoing expenses.
Together, they offer a more complete picture of cover without duplicating benefits.
Which Should You Choose?
It depends on your priorities and budget.
Consider PMI if you:
- Want fast access to private consultations and surgery
- Have a family history of conditions requiring specialist care
- Value choice over where and when you’re treated
- Can budget for higher monthly premiums
Consider a cash plan if you:
- Mainly need help with routine costs like dental and optical
- Want low-cost cover with no medical questions
- Already have NHS care you’re comfortable with for major treatment
- Are looking for an affordable employee benefit
Consider both if you:
- Want comprehensive protection across routine and major care
- Prefer to keep out-of-pocket costs low for everyday health needs
A Practical Next Step
The right choice isn’t always obvious, and policies vary widely in what they include. If you’re unsure whether PMI, a cash plan, or a combination makes sense for your situation, get in touch or compare quotes. We’ll help you match the cover to your actual needs – no jargon, no pressure.